Orders in hand is the day the clock starts, and this desk is built around that clock.
A move on orders has three inputs an ordinary purchase does not: an allowance that arrives on a fixed schedule, a report date that sets every other date, and a loan program with its own rules on fees, appraisal, and occupancy. Each one is quoted here from its published source.
Military families come to a Front Range agent for different reasons, and each situation runs differently.
You have orders to Colorado and you are house hunting from another time zone.
Tours run by video the same week they are requested, the inspection is scheduled alongside the offer, and every figure arrives in writing so a decision can be made without a flight.
You are leaving Colorado and the house has to sell against a report date.
The listing calendar is built backward from the date you have to be gone, and the pricing memorandum accounts for the season you are actually selling into rather than the one you would have chosen.
You are separating or retiring and staying in the state.
Leaving the service is a large change and the money changes with it, which is a lot to hold at once. The allowance stops, so the payment has to be set against what follows it. We model that transition before an offer rather than after, and the disabled veteran property tax exemption is part of the arithmetic.
You are a surviving spouse using benefits you have not used before.
You should not have to research any of this while you are grieving, so I will do that part and bring you the answer. Dependency and Indemnity Compensation recipients are exempt from the VA funding fee, and Colorado carries a Gold Star spouse property tax exemption. Both are quoted here with their sources.
You are a service member buying a first rental near post.
The occupancy certification is a real constraint on a VA purchase, and the entitlement arithmetic changes once part of it is committed. Both are modelled before anything is written.
You are a National Guard or Reserve member with your own eligibility rules.
Guard and Reserve service establishes VA loan eligibility on a different service requirement, and the Certificate of Eligibility request follows a different path. Bring the orders and we will work out which applies.
Five installations sit inside the Colorado Springs housing area and one inside Denver.
The housing area, not the gate you drive through, is what sets the allowance. That single fact decides more about a search than any other, because two families reporting forty miles apart can be working from allowances several hundred dollars apart.
- Colorado Springs, military housing area CO046.
Fort Carson, Peterson SFB, Schriever SFB, United States Air Force Academy, Cheyenne Mountain SFS. One allowance covers all five, so a family reporting to Schriever and a family reporting to the Academy see the same figure at the same grade.
- Denver, military housing area CO045.
Buckley SFB. The Denver allowance runs materially higher at every grade, and the housing stock and commute pattern differ from the Springs in ways worth planning around.
- An assignment that straddles both is planned around the report location.
Where duty pulls a family between the two areas, the allowance follows the duty station on the orders, and the search has to be built from that figure rather than from the more generous one.
Both Colorado housing areas are published grade by grade, with and without dependents.
The Colorado Springs housing area covers Fort Carson, Peterson SFB, Schriever SFB, United States Air Force Academy, Cheyenne Mountain SFS. The Denver housing area covers Buckley SFB. The 2026 rates took effect on the first of January and carry a national average increase of 4.2 percent.
| Pay grade | Colorado Springs (CO046) | Denver (CO045) | Difference |
|---|---|---|---|
| E-1 | $2,160 | $2,556 | $396 |
| E-2 | $2,160 | $2,556 | $396 |
| E-3 | $2,160 | $2,556 | $396 |
| E-4 | $2,160 | $2,556 | $396 |
| E-5 | $2,358 | $2,841 | $483 |
| E-6 | $2,433 | $3,063 | $630 |
| E-7 | $2,487 | $3,114 | $627 |
| E-8 | $2,553 | $3,168 | $615 |
| E-9 | $2,646 | $3,267 | $621 |
| W-1 | $2,448 | $3,081 | $633 |
| W-2 | $2,514 | $3,135 | $621 |
| W-3 | $2,598 | $3,210 | $612 |
| W-4 | $2,664 | $3,288 | $624 |
| W-5 | $2,754 | $3,396 | $642 |
| O-1E | $2,496 | $3,120 | $624 |
| O-2E | $2,583 | $3,195 | $612 |
| O-3E | $2,679 | $3,306 | $627 |
| O-1 | $2,376 | $2,874 | $498 |
| O-2 | $2,430 | $3,060 | $630 |
| O-3 | $2,595 | $3,207 | $612 |
| O-4 | $2,778 | $3,426 | $648 |
| O-5 | $2,913 | $3,588 | $675 |
| O-6 | $2,934 | $3,615 | $681 |
| O-7 | $2,955 | $3,642 | $687 |
A service member who maintains uninterrupted BAH eligibility at a given location will not see a rate decrease. Several Denver with dependents rates are lower for 2026 than for 2025, so a member who arrived in 2025 keeps the higher figure while a member arriving in 2026 receives the 2026 figure. BAH is set to cover 95 percent of the national average housing cost by pay grade; the member cost share is 5 percent. Source: Department of War release, 2025-12-11.
The allowance sets the payment a purchase has to answer to, and the translator does that arithmetic.
Choose the housing area and the grade, and the allowance fills in from the table above. The instrument then builds the full payment including the financed funding fee, taxes, insurance, and dues, and it reports the gap in both directions rather than only the flattering one.
With a monthly BAH of $2,358 for E-5 with dependents in the Colorado Springs housing area, the full payment of $3,485 runs $1,127 a month beyond the allowance, so BAH covers 68 percent of it.
This is a model, not a loan offer or a certificate of eligibility. A VA loan carries no private mortgage insurance, the funding fee is financed into the balance here, and the rate of 6.71 percent is assumed to hold for the full term. The fee depends on your down payment and prior use, and it is waived for many veterans with a service connected disability rating and for Purple Heart recipients, so confirm your exact fee with your lender or the VA. Per grade figures verified across three agreeing secondary sources and the official 2025 file; confirm on the official lookup before acting on a single figure.
The features of the VA loan decide most of what a military purchase can do.
Each is quoted from the VA purchase loan page as updated 2026-01-07, and each has a consequence for how an offer is written rather than only a definition.
- No down payment is required when the sales price does not exceed the appraised value.
Full entitlement carries no VA loan limit at all, so the constraint is what a lender will approve and what the appraisal supports, not a published ceiling.
- No private mortgage insurance and no mortgage insurance premium apply to a VA loan.
That single difference is often larger than the funding fee across the first several years, which is why the two are compared inside the translator rather than argued about in the abstract.
- The loan carries no prepayment penalty, so every extra dollar of principal reaches the balance.
The payoff engine on this site assumes exactly that, and a VA loan is one of the few products where the assumption holds without a clause to read first.
- A VA loan may be assumed by a later buyer, including a buyer who is not a veteran.
The loan must be current, the assumer takes full liability and must be creditworthy under VA standards, and the assumption fee of half a percent is collected at close and may not be financed.
- Closing costs may be paid by the seller as a concession within VA limits.
In a market at four months of supply that concession is a negotiable term, and it is written into the offer rather than raised after inspection.
- Occupancy is certified at closing, and a spouse may satisfy it during a deployment or a set of orders.
The VA Lenders Handbook asks for occupancy within a reasonable time, generally read by lenders as sixty days, with defined circumstances allowing longer.
The funding fee is a published table, and certain circumstances remove it entirely.
Rates apply to loans closing on or after April 7, 2023 and before November 14, 2031, per VA Circular 26-23-06.
| Down payment | First use | After first use |
|---|---|---|
| Less than 5 percent | 2.15 percent | 3.30 percent |
| 5 percent or more, less than 10 percent | 1.50 percent | 1.50 percent |
| 10 percent or more | 1.25 percent | 1.25 percent |
| County | One unit limit | Maximum guaranty |
|---|---|---|
| El Paso County, Colorado Springs, Fort Carson, Peterson, Schriever, and the Air Force Academy | $832,750 | $208,188 |
| Denver County, and Adams, Arapahoe, Broomfield, Douglas, and Jefferson | $862,500 | $215,625 |
| Teller and Pueblo counties, at the 2026 national baseline | $832,750 | $208,188 |
Five circumstances remove the funding fee, and any one of them is sufficient.
- Exemption 01
You are receiving VA compensation for a service connected disability.
- Exemption 02
You are eligible to receive VA compensation for a service connected disability, but you are receiving retirement or active duty pay instead.
- Exemption 03
You are receiving Dependency and Indemnity Compensation as the surviving spouse of a veteran.
- Exemption 04
You are a service member who received a proposed or memorandum rating before the loan closing date stating that you are eligible for compensation because of a pre discharge claim.
- Exemption 05
You are an active duty member of the armed forces and, on or before your loan closing date, you provide evidence that you received a Purple Heart.
Full entitlement carries no VA loan limit. A borrower with used entitlement subtracts the amount already charged from the county maximum guaranty to find the remaining bonus entitlement. Source: VA.gov loan limits page, updated 2025-08-12. The VA modernized its Minimum Property Requirements effective May 1, 2026. The mandatory radon testing requirement was removed, standards for properties built before and after 1978 were revised, and guidance on detached structures was streamlined. Radon remains worth testing in Colorado regardless of what the loan requires, because every Colorado county sits in the highest EPA zone.
The peak moving window changes what a search looks like more than the price does.
The services run their peak season from May 15 to August 31, which carries between forty and sixty five percent of the year's household goods moves, depending on the service reporting. The Colorado Springs listing calendar moves with it, so the same budget meets a different set of houses in June than it does in November.
Roughly forty percent of the year's new listings arrive inside those four months, which is why an orders date in March is a different search from an orders date in October.
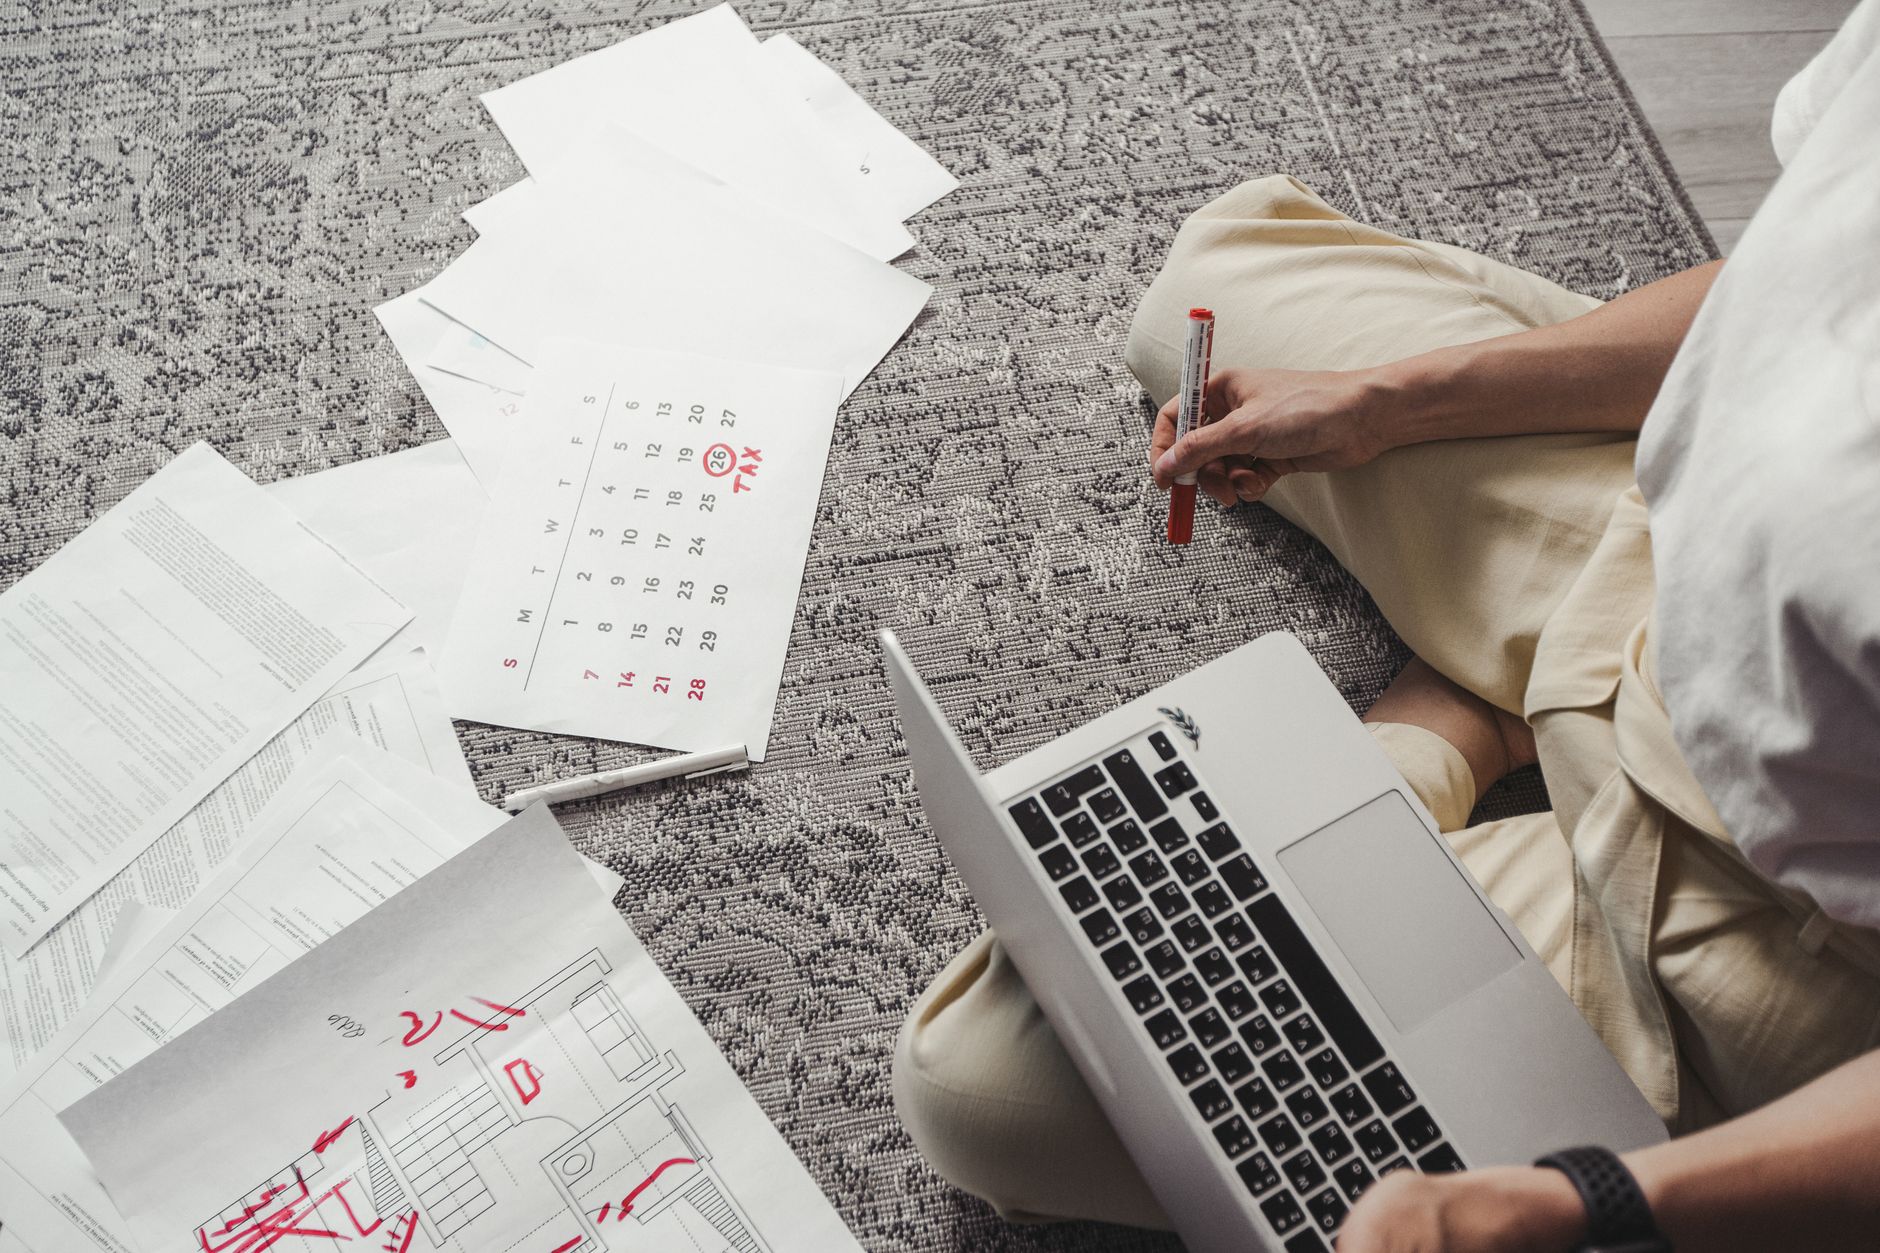
Every date in a move on orders is derived from the report date, so we set that first.
- Orders in hand, through week twoThe calendar is fixed before anything else moves.
The report date sets every other date. We work backward from it to a closing date, a listing date if you are selling, and the last day a lender can receive a complete file without paying for a rate extension.
- Weeks two through fourEntitlement and the loan file are settled before a search begins.
The Certificate of Eligibility, the funding fee status, and whether entitlement is full or partial decide the ceiling. A partial entitlement file uses the county limit, which is $832,750 in El Paso County and $862,500 in Denver County for 2026.
- Weeks four through eightThe search runs against the allowance, and what you are hoping for is written down beside it.
The translator sets the payment the allowance supports at your grade and housing area, and only properties clearing it are toured. Where you are still at your losing station, tours run by video with the inspection scheduled the same week as the offer.
- Weeks eight through twelveThe contract, the appraisal, and the inspection run in parallel against the report date.
A VA appraisal averages about seven business days. The inspection is read as a repair budget with figures, and repair requests are written to preserve the closing date rather than to win a point.
- The final two weeksTemporary lodging and the move are planned as though the closing may slip.
Temporary Lodging Expense at the gaining station and the household goods delivery window are arranged with a fallback, because a closing date that moves by four days should not put a family in a hotel without a plan.
A move on orders is hard on a family, and a few facts are enough for me to start carrying part of it.
Send me the report date, the housing area you are reporting to, and your grade with dependent status. That is enough for me to return the allowance, the payment it supports, and the search window before we speak.